
Agentic AI and Institutional Intelligence Reshape Banking by 2027
Agentic AI is moving from experimentation into banking workflows, with autonomous agents beginning to execute payments and manage transactions for customers. That development carries a direct challenge to traditional deposit economics: if software agents handle more of the movement of money, banks may find their deposit franchises squeezed by new forms of intermediation.
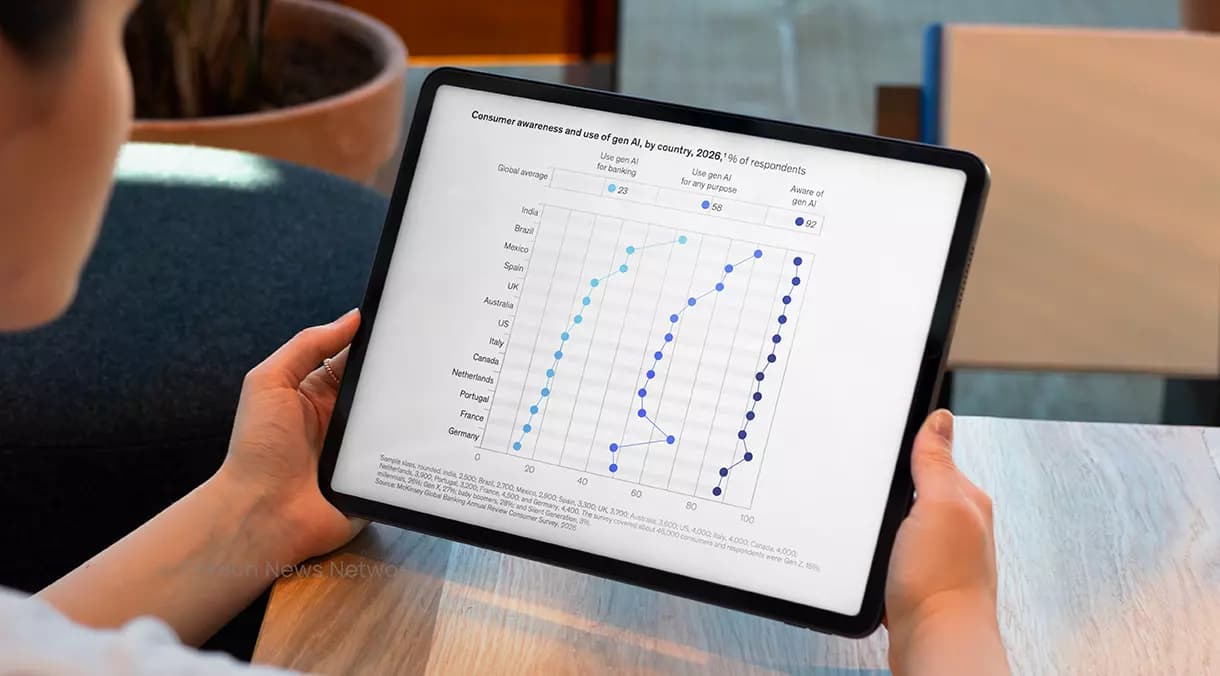
Large language models are also taking on a larger role than that of simple interfaces. They are becoming intermediaries between customers and banks, and in doing so they are emerging as new distribution channels. Lenders that view LLMs only as chatbots could lose the primary customer relationship to platforms that coordinate financial tasks.
Institutional intelligence is the organizing idea for 2027. For banks, it means combining data, controls and governance so that AI can be deployed safely at scale. The competitive difference will come less from access to models and more from the ability to integrate agents into risk, compliance and product operations without losing oversight.
The strategic question for incumbents is whether agentic AI strengthens their franchise or erodes it. Banks that redesign processes around autonomous execution - while preserving human accountability - can defend deposits and compete for distribution. Slower rivals risk becoming balance-sheet utilities sitting behind third-party AI channels, ceding the customer interface and the economics that come with it.
Source: fintechnews.ch